Buyer guide
What hurricane and flood insurance actually costs now
By Doug Richman · about 6 min · reviewed October 2026
Ask any recent South Florida buyer what surprised them and the answer is rarely the mortgage rate. It is the insurance quote. Coverage here is genuinely more expensive than most of the country, but the range between a well-prepared house and an unprepared one is enormous, and most of what drives the difference is knowable before you offer.
Often the first eligibility and pricing question for a South Florida carrier.
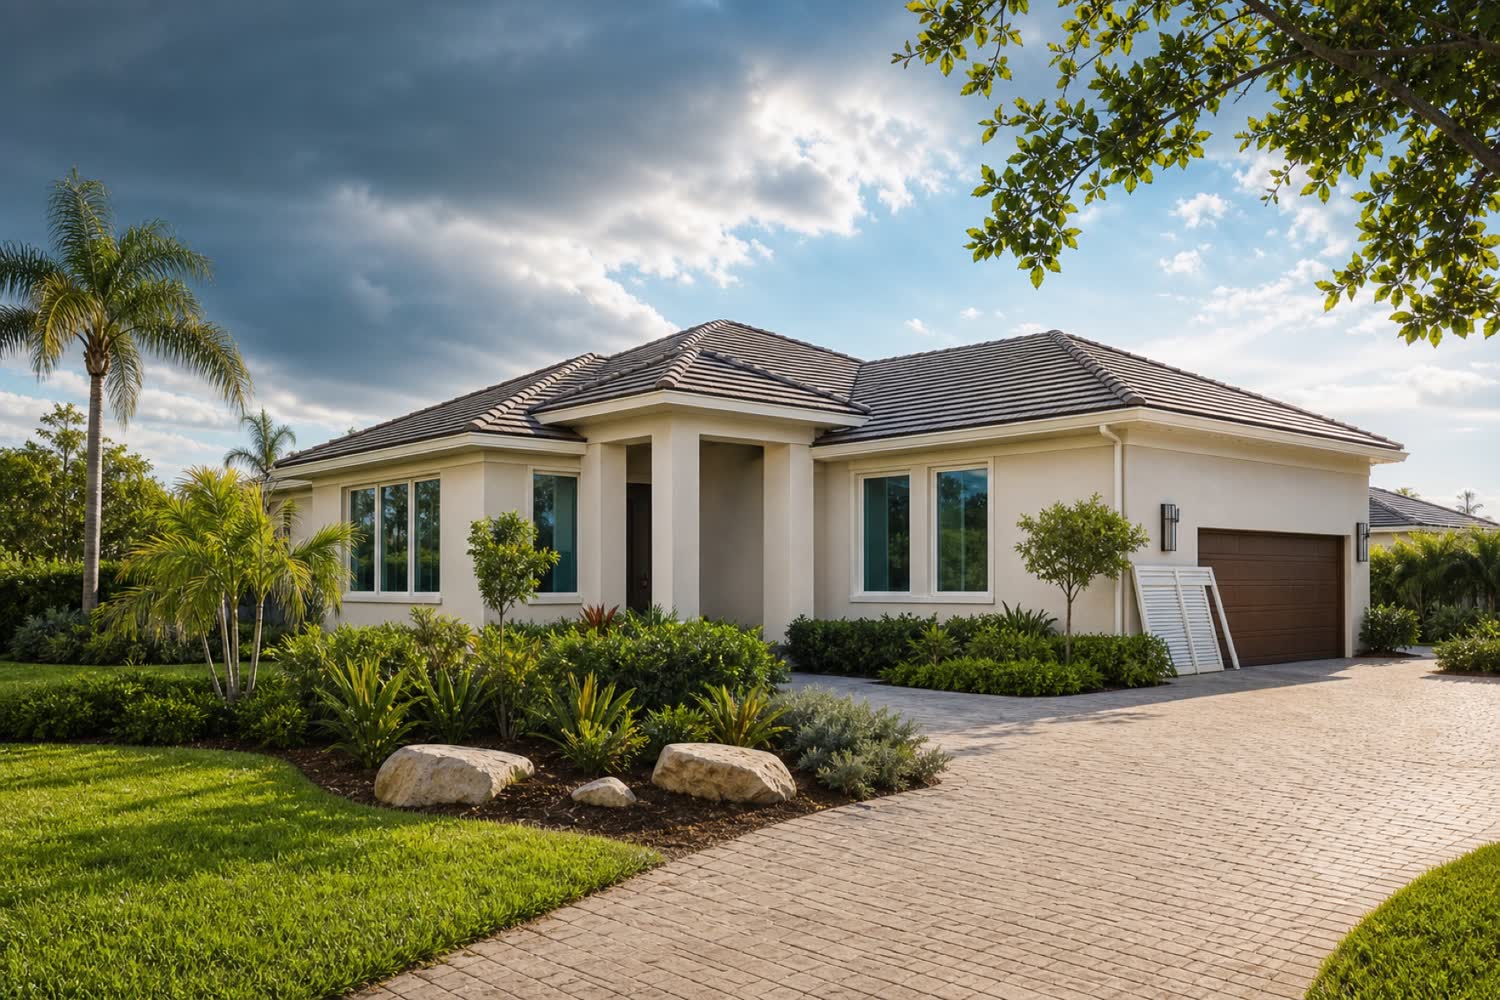
Windows, doors, and the garage door can materially change wind credits.
Flood risk is separate from standard homeowners coverage and deserves its own quote.
Relative influence is illustrative, not a premium formula. Obtain property-specific wind and flood quotes during the inspection period.
Three policies, not one
A South Florida homeowner typically carries a standard homeowners policy, windstorm coverage (inside the policy or separate), and flood insurance. Flood is the one buyers skip at their peril: standard policies do not cover rising water, lenders only require flood coverage in mapped high-risk zones, and some of the worst recent flood losses happened outside those zones. If your home is insured through Citizens, flood coverage is not optional at all: it is required on every Citizens homeowners policy that covers wind by January 1, 2027, in or out of a flood zone, and already on homes insured for $400,000 or more. Condo unit owner policies are exempt.
What actually moves the price
Insurers here price the roof before almost anything else. A roof near the end of its insurable life can make a home hard to cover at any price, which turns roof age into a negotiation item, not a cosmetic one.
- Roof age and shape: newer and hip-shaped roofs price dramatically better
- A wind mitigation inspection: usually well under $200, and it routinely pays for itself many times over in windstorm credits
- Opening protection: impact windows and rated garage doors earn real discounts
- Year built: homes built to post-2002 codes price in a different tier
- Elevation and flood zone, which you can check before ever making an offer
Get the quote before you sign, not after
The practical rule: get an actual insurance quote, plus the four-point and wind mitigation inspections, inside your inspection period. A surprise quote is grounds to renegotiate while you still have leverage. I keep a shortlist of agents who quote quickly for exactly this reason, and for older roofs we often negotiate a roof credit or replacement into the contract itself.